Apartment for sale in Marseille 10ème arrondissement — 3 bedrooms, 62 m²
Marseille 10ème arrondissement, Provence-Alpes-Côte d'Azur, France
€65,000
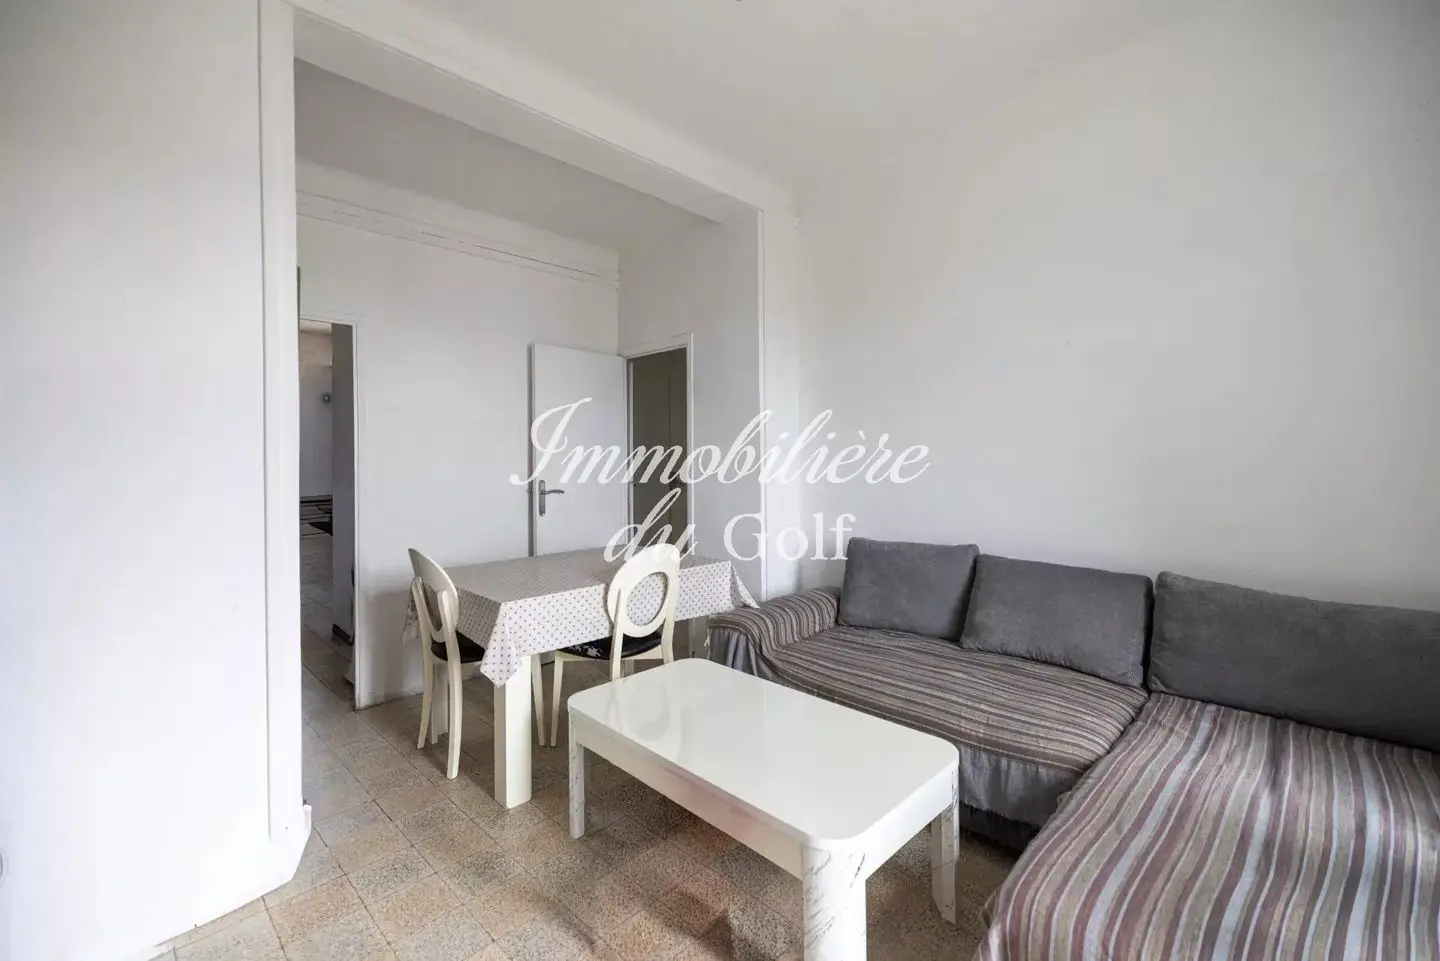
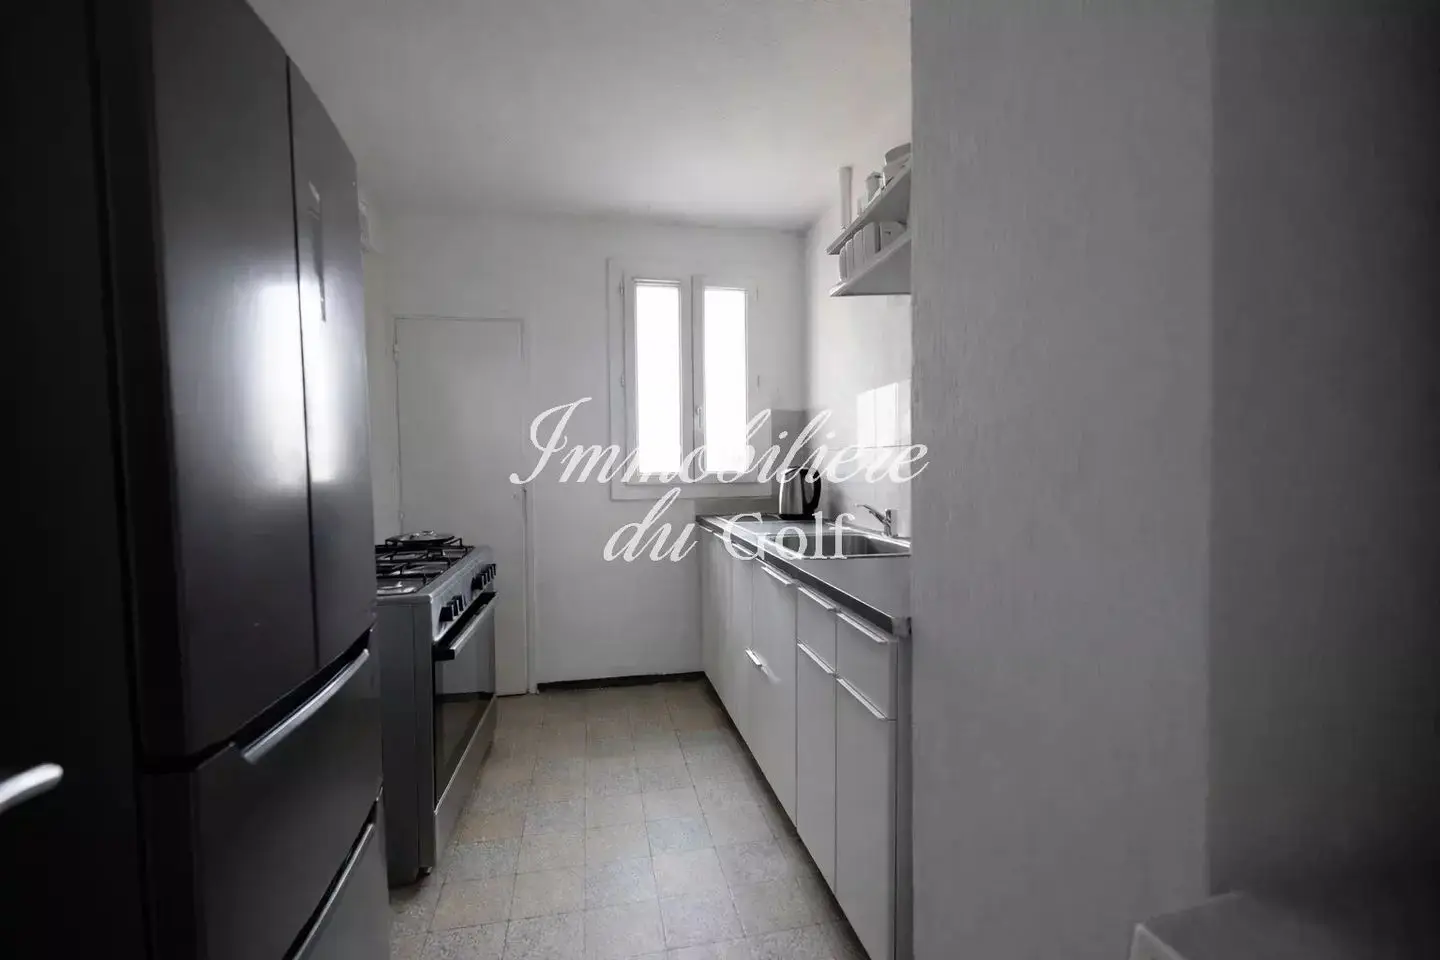
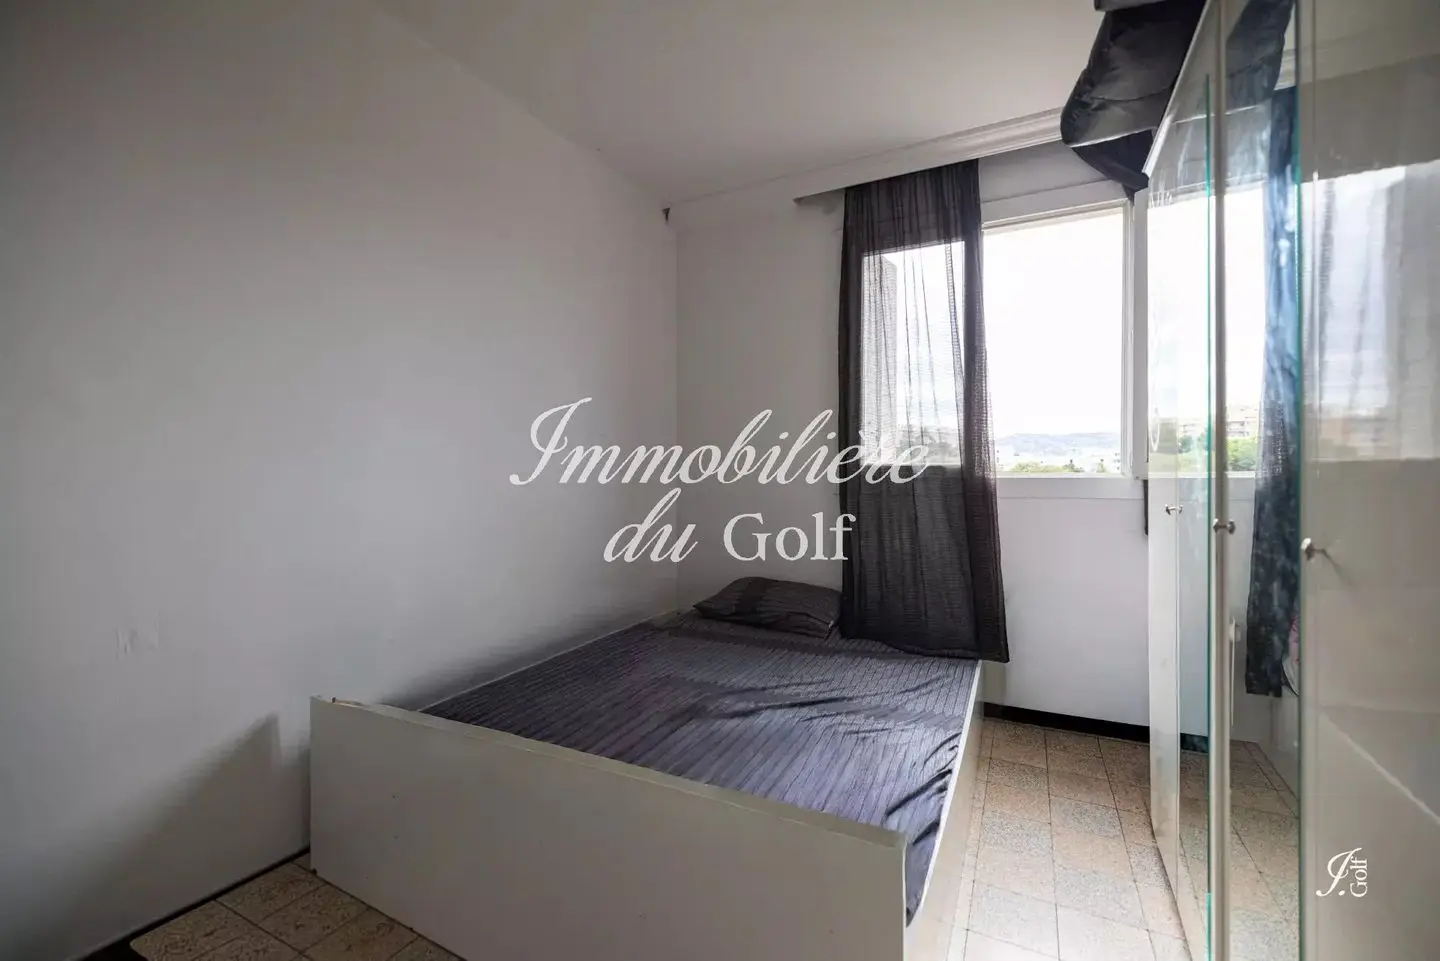
Key facts
- Bedrooms
- 3
- Interior
- 62 m²
- Type
- apartment
About this property
Location
Approximate location based on the listing's town. Confirm the exact address with the agent.
How to buy this property
Typical process in France — 3–4 months from accepted offer to keys. Tell us where you're buying from:
What's different for you
- You can usually reuse your French bank for the mortgage — expect up to 100% loan-to-value for a main home if your income allows (HCSF debt cap: 35% of income).
- If this will be your main home, it is exempt from capital gains tax when you sell.
What's different for you
- No ownership restrictions and no visa needed to live here — you can move in whenever you like.
- French banks lend to EU non-residents, but usually only up to 70–80% of the price and they want French or EU income evidence.
- When you sell, capital gains are taxed at 19% plus a 7.5% solidarity levy (26.5%), not the full 17.2% social charges.
- Sign by power of attorney (procuration) if you can’t attend completion in person.
What's different for you
- Anyone can buy in France — there are no nationality restrictions on ownership.
- Owning property does not give you residency: without a long-stay visa you are limited to 90 days in any 180 (this applies to UK buyers since Brexit).
- Mortgages are harder: typically 50–70% loan-to-value, and many banks decline US citizens because of FATCA reporting.
- Opening a French bank account remotely can take weeks — start early, the notaire will want funds from an identifiable account.
- When you sell, gains are taxed at 19% + 17.2% social charges (36.2%), and sales above €150,000 need an accredited tax representative.
Next steps
-
1
Viewing and written offer (offre d’achat)
1–2 weeksMake a written offer through the agent. Once the seller accepts in writing the price is agreed, but nothing is binding on you until the compromis.
-
2
Compromis de vente
2–4 weeks after the offerThe preliminary contract, drawn up by a notaire or the agent. It includes the mandatory diagnostic reports (DDT) and any conditions such as getting a mortgage. You pay a 5–10% deposit into escrow.
For you: You can sign electronically or by power of attorney — you don’t need to fly over for this step.
-
3
10-day cooling-off period
10 daysPrivate buyers of homes can withdraw for any reason within 10 days of receiving the signed compromis, and get the deposit back in full.
-
4
Mortgage and notaire searches
6–10 weeksYou have about 45–60 days to get a mortgage offer (if the compromis includes a loan condition). Meanwhile the notaire checks title and planning, and whether the town or SAFER (for rural land) wants to use its pre-emption right.
For you: Non-resident mortgages often take the full 60 days, so ask for a longer loan condition in the compromis.
-
5
Acte de vente and keys
1 dayYou sign the final deed at the notaire’s office (or by power of attorney), transfer the balance plus fees beforehand, and get the keys the same day.
Buying costs on €65,000
|
Notaire fees and transfer tax (“frais de notaire”) 7–8.5% for older homes (2–3% for new builds) Mostly transfer duties: about 5.8–6.3% depending on the département. The notaire’s own fee is under 1%. |
€4,550–€5,525 |
|
Estate agent fee Usually already in the asking price “FAI” (frais d’agence inclus) means the advertised price includes the agent’s 4–8%. If it says “net vendeur”, add it on top. |
— |
|
Independent survey (optional) €500–€1,500 A structural survey isn’t standard in France, but it’s worth it for older stone houses. |
€500–€1,500 |
|
Mortgage costs (if borrowing) ~1–2% of the loan Arrangement fee, loan guarantee or charge on the property, and broker fee. |
€0–€1,300 |
| Estimated total on top of the price | €5,050–€8,325 |
Pitfalls to watch
- Septic tanks (fosse septique): a non-compliant SPANC report means you have to upgrade within 1 year, often €8,000–€15,000.
- Unpermitted extensions, pools or barn conversions: check the plans and permits against what you see. The notaire only checks what’s on paper.
- Energy rating (DPE) F or G: G-rated homes can no longer be let on new leases, and F-rated homes follow from 2028. That matters if you plan to rent it out.
- Second homes pay taxe d’habitation, and some towns with housing pressure add up to 60% on top. Ask the seller for the latest bill.
- French inheritance rules reserve part of the estate for children. Non-French buyers can choose their own nationality’s law in a will (EU Succession Regulation), so take advice before you sign.
- Short-term letting now needs registration with the town hall, and many towns cap or ban it. Check before you rely on Airbnb income.
General guidance, last reviewed October 2026 — not legal or tax advice. Rules change and every purchase is different, so confirm with an independent local lawyer or notary before you sign anything.
Buying property in France
Read our complete guide — fees, visas, taxes, and everything overseas buyers should know before making an offer in France.
Read the France buying guide